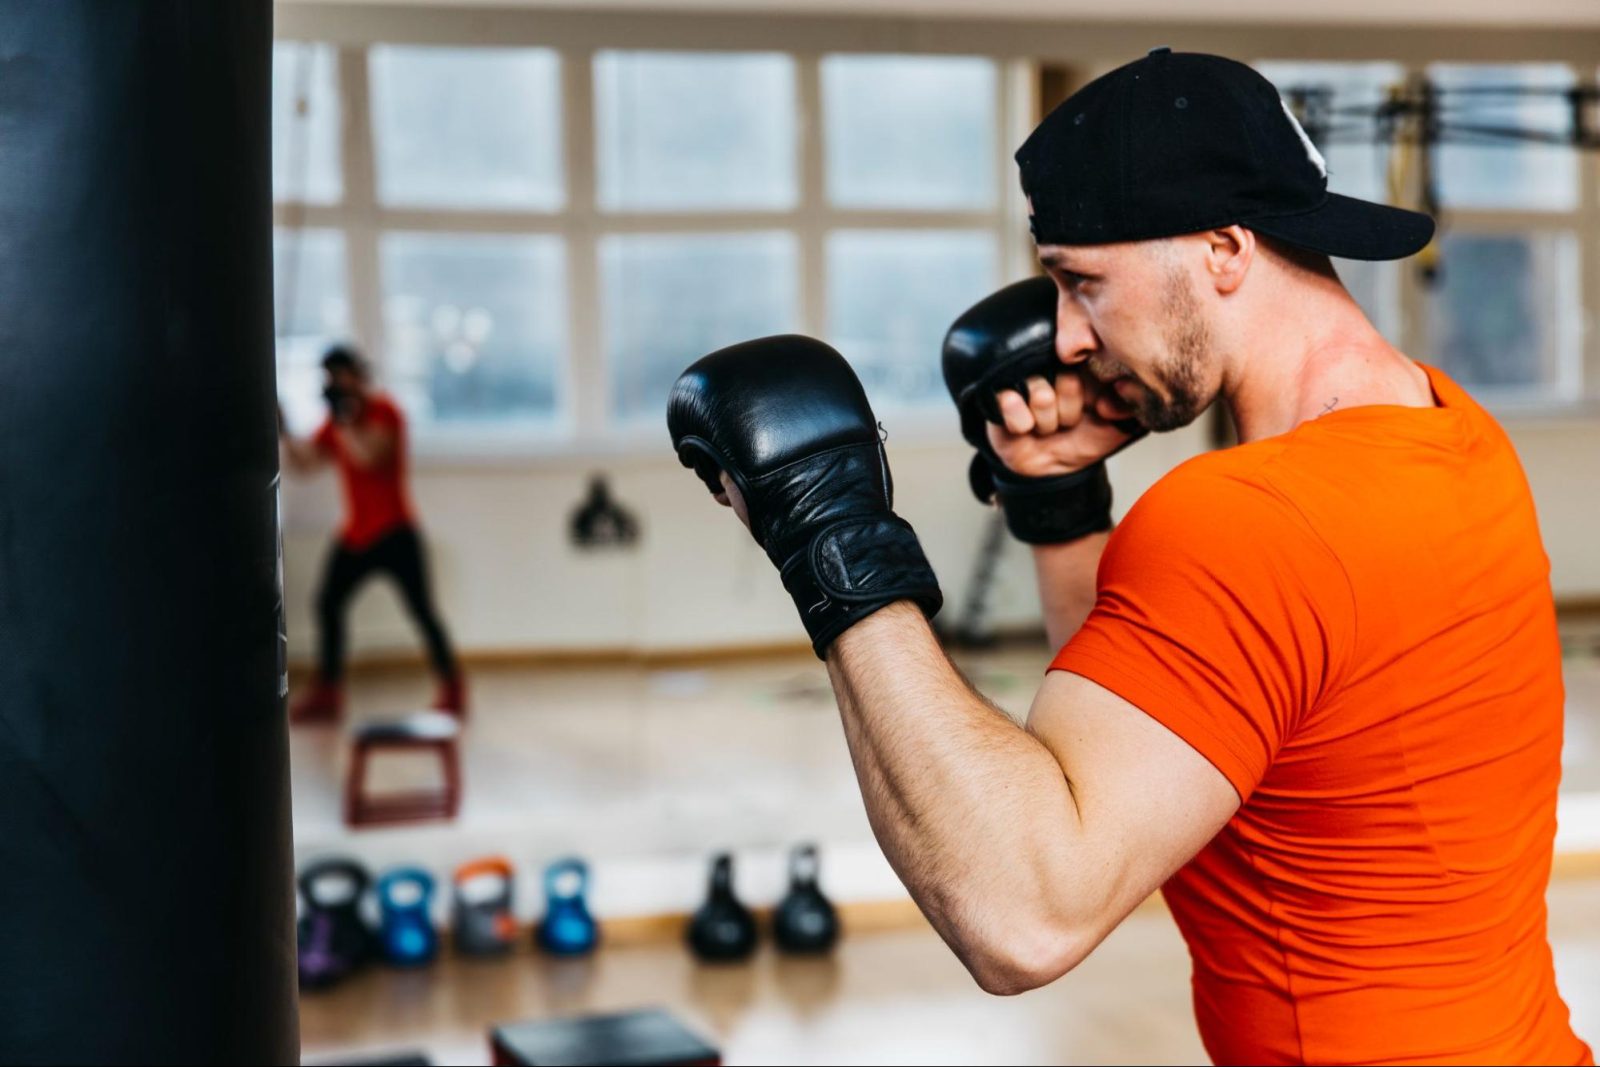
Managing a boxing gym is not only about training the athletes and establishing a good training community. You also need to manage risks every day. A student may be injured in sparring, a visitor may slip around the ring, or costly equipment may be damaged. In the absence of adequate insurance, any unforeseen event can result in legal fees, repair costs, or financial strain on your company.
To select the appropriate coverage, the first step is to understand how your gym works. Ordinary business insurance might not cover participants, injuries, or boxing competitions. Therefore, before selecting a plan, you should compare the policies, read exclusions, and determine the gaps. Taking these steps can help you protect your business and make informed decisions.
So, what insurance does a boxing gym need?
This guide identifies five important types of insurance, describes situations in which each might be essential, and explains what to consider before buying insurance coverage.
Table of Contents
1. General Liability Insurance for Third-Party Claims
General liability is an important insurance policy for your gym. Suitable boxing gym insurance may help cover eligible third-party bodily injury and property damage claims. For example, a visitor could trip over equipment in your reception area. Similarly, an event may result in injuries to a spectator. Legal defense costs and settlements may be covered for eligible claims, depending on the policy.
Before buying a policy, confirm that the insurer covers your specific boxing activities. Some policies disallow or limit coverage for contact sports and participant injuries. Therefore, explain whether you offer sparring, youth classes, fitness boxing, or amateur competitions. Request clarification on any exclusions that may have implications for your business.
The boxing training facility liability insurance must correspond to your actual risks. For this reason, compare coverage limits, deductibles, and waiver requirements. A signed waiver does not automatically prevent a lawsuit or remove every liability exposure. Therefore, determine whether your policy covers the activities you offer rather than assuming that all gym operations are included.
2. Commercial Property Insurance for Equipment
Commercial property insurance may protect your gym equipment against covered losses, such as fire, theft, or vandalism. For example, your property might consist of heavy luggage, gloves, mats, lockers, computers, and other training gear. Additionally, when you are the owner of the building, make sure that the structure is covered in the policy as well.
To assess your coverage needs, start by listing your equipment and estimating replacement costs. Also, maintain receipts, photos, and purchase documentation as a means of establishing coverage needs and to help substantiate any possible claims. In addition, check whether the policy pays replacement cost or actual cash value.
However, boxing rings are not necessarily included under a typical gym insurance policy. Instead, the coverage varies with policy conditions, installation, and the cause of damage. Therefore, when comparing boxing ring insurance, ensure that the platform, ropes, padding, and accessories are insured. Finally, review any special limits, deductibles, and exclusions before purchasing a policy.
3. Participant Accident Coverage for Training Injuries
Boxing is a physically demanding sport that entails rigorous training. Despite strict supervision, participants may still get injured during drills or sparring. In such cases, participant accident coverage may help pay eligible medical expenses after a covered accident, subject to plan terms and limits.
However, participant accident coverage differs from general liability insurance. While accident benefits may help cover eligible medical expenses, liability insurance addresses claims alleging that your business was responsible for an injury. Therefore, ask whether your policy covers members, trial participants, minors, visiting athletes, and competitors.
Before purchasing coverage, explain your gym activities to the insurer. For example, a boxing gym that offers fitness classes may have different insurance needs from one that conducts regular sparring sessions. If you also host competitions or camps, confirm that your policy covers those activities.
4. Professional Liability for Coaching Services
Your coaching services carry risks beyond on-site accidents. Participants may claim that unsafe advice or poor supervision caused an injury. Professional liability insurance may cover eligible claims involving professional negligence, subject to policy terms and exclusions.
If you employ coaches or hire independent instructors, check who qualifies as an insured. Contractors may need separate policies if your coverage excludes their work. Written agreements can clarify responsibilities but do not replace insurance.
Maintain current instructor qualifications, document incidents, and enforce safety rules. These steps reduce risks, while insurance addresses covered claims. Neither replaces responsible supervision. Review your policy regularly to ensure your coverage matches your coaching services and training activities.
5. Additional Coverage for Business Risks
Your gym may need extra coverage based on its operations and assets. Business interruption insurance may help replace lost income after a covered event forces a temporary closure, while equipment breakdown coverage may protect against certain mechanical or electrical failures. Check limits, waiting periods, and exclusions before choosing either option.
If you host boxing matches, tournaments, or exhibitions, ask about event-specific insurance. Your regular policy may not cover every competition or spectator risk. Confirm any insurance requirements with venues and event partners before signing contracts or announcing an event.
Cyber liability coverage may also be useful if you store member data or process digital payments. Since a data breach can create costs that standard liability insurance may not cover, review your risks with an insurance professional to identify gaps and choose suitable additional protection.
Conclusion
Choosing insurance for your boxing gym requires more than comparing prices. Review general liability, property, participant accident, and professional liability coverage. Then consider additional protection for equipment breakdowns, business interruptions, cyber incidents, and organized events. Your needs depend on your activities, assets, contractual obligations, and policy exclusions.
Before purchasing coverage, prepare an equipment inventory and list every service you provide. Ask your insurer about sparring injuries, participant medical expenses, boxing ring damage, and competitions. Compare coverage limits and exclusions, request written clarification, and choose a policy that fits your gym operations.